
Facts on EDITORIAL REVIEW
Article series
Swedish Gambling HistoryPart 4 of 4Start with Part 1: Selling the dream
From Monopoly to Marketplace
Sweden, 2001–2025: digital competition, licensing reform and the continuing role of state-exclusive gambling.
The internet challenged a gambling system organised around national permissions and established domestic operators. Sweden’s response in 2019 was a mixed system: competition under licence for online casino and betting, alongside gambling reserved for the state or public-benefit organisations. The closure of Casino Cosmopol in 2025 did not abolish the remaining state-exclusive categories.
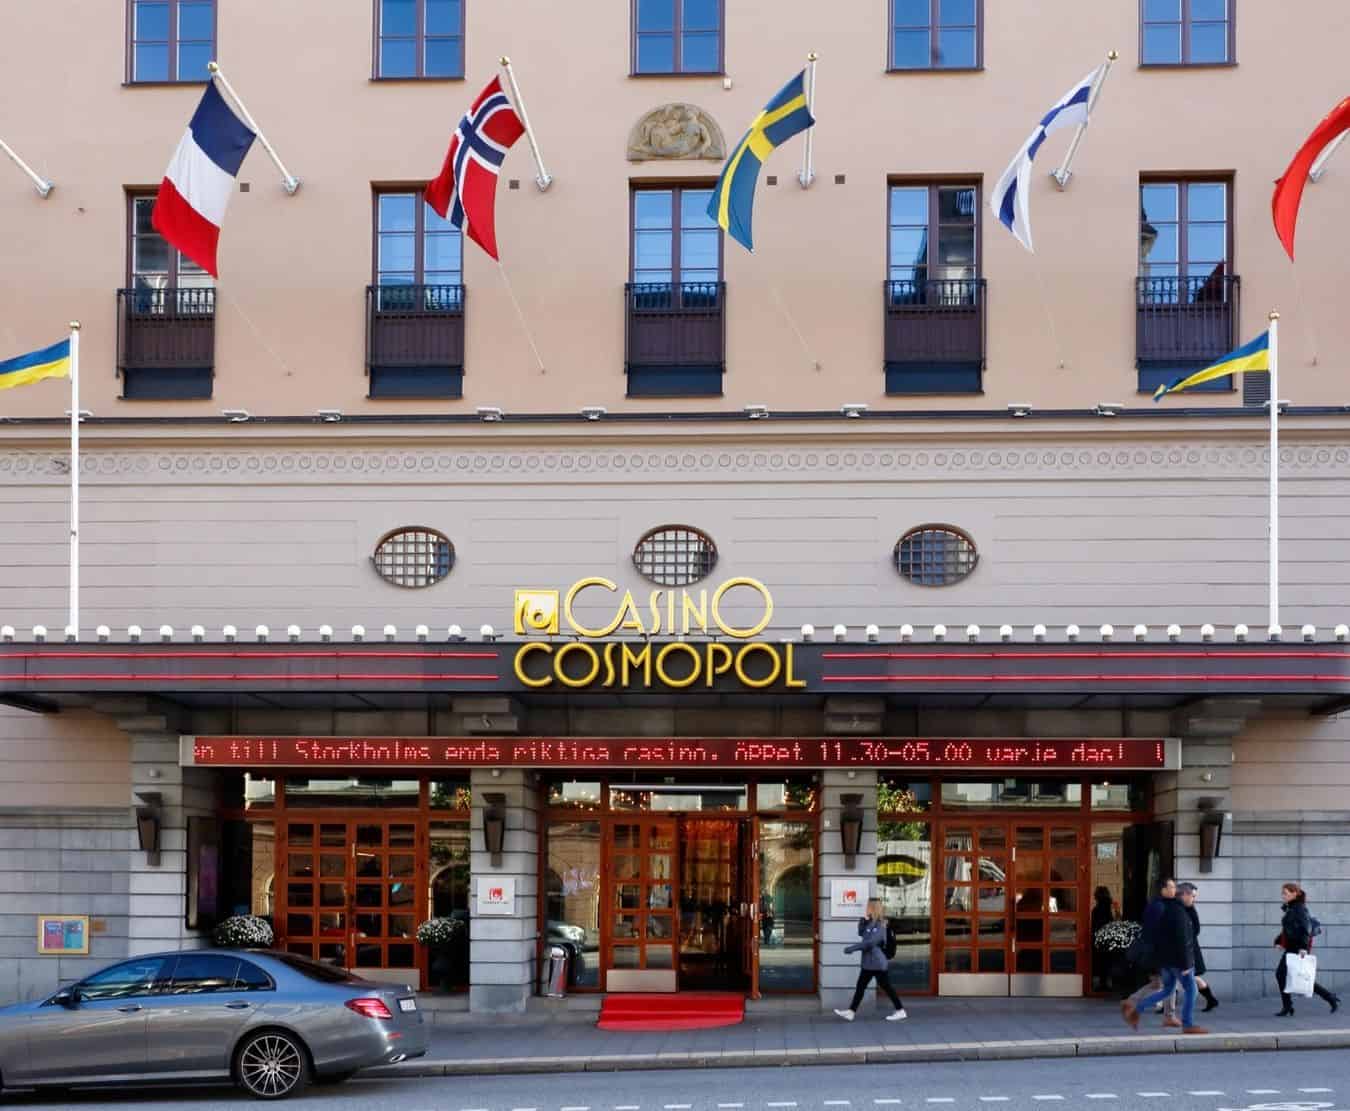
Closing of Casino Cosmopol in Stockholm. Photo: Roland Magnusson / Alamy
Setting the Scene
The key change was not simply that more advertising moved to screens. An operator could reach Swedish customers while being established and regulated elsewhere. Regulators then faced a practical question: how could they bring that activity within domestic oversight?
A licence in another EU country did not automatically authorise access to Sweden. The European Commission explains that gambling licences are not subject to obligatory mutual recognition. National restrictions must nevertheless meet EU-law requirements. Source: European Commission.
This distinction separates the technological opening of a market from its legal opening. Both mattered to the businesses competing for Swedish players.
Key Dates
- 2004: Malta publishes its Remote Gaming Regulations.
- 2019: Sweden’s new licensing system takes effect on 1 January.
- 2025: Casino Cosmopol Stockholm closes to guests on 25 April; the legislative removal of that casino category was scheduled for 1 January 2026. Sources: Malta Gaming Authority, Swedish reform legislation and Svenska Spel.
Historical scope: this article describes developments through 2025. Proposals for later implementation are identified as proposals, rather than treated as rules already in force.

Editorial illustration of Svenska Spel’s “Spela lagom” (play in moderation) message.
Campaigns, Messaging and Audience
Competition under licence did not mean unrestricted promotion. The 2019 framework combined market access with consumer-protection obligations. For a brand, the challenge was therefore to make an offer visible while complying with the rules governing how it was presented.
This is a more precise way to understand the change than a simple contrast between restrained state messaging and aggressive private advertising. A campaign’s content, placement and audience need to be examined regardless of who owns the operator.

Illustrating Sweden’s 2019 Gambling Act—Moderation, Bonuses, and Reform
Channels, Regulation and Public Debate
Swedish rules require moderate gambling marketing, prohibit targeting it specifically at under-18s, and restrict bonuses to the first occasion on which a customer plays with a licensee. These are specific obligations, rather than a general prohibition on digital advertising. Source: Konsumentverket.
Spelinspektionen’s 2023 review records SEK 7.3 billion in gross advertising expenditure in traditional media for 2018, falling to SEK 5.7 billion in 2019. These figures describe a particular measurement of media purchases—not audited net expenditure across every digital channel. See section 5.4.2 of the report.
In September 2025, the government proposed extending the existing ban on licensees and agents providing credit. The bill concerned implementation in 2026, rather than a broad credit-card ban already in force in 2025. Source: Proposition 2025/26:11.
What Advertising Evidence Can Establish
Visibility, trust and harm are separate outcomes. Evidence that advertising is common does not show that a particular operator is more trusted, and a general gambling survey should not be presented as an evaluation of influencer campaigns unless it measured them.
Binde’s review of advertising research cautioned against both assuming a large causal effect on problem gambling and assuming that advertising merely shifts market share. See Selling dreams – causing nightmares? (2007). That distinction remains useful when reading historical claims about persuasion.
Transparency and Financial Flows
The 2019 reform should not be reduced to a transfer from “money for society” to “private money”. Different channels of funding coexist: taxes, state dividends, commercial sponsorship and proceeds distributed by public-benefit organisations. Their amounts and recipients need to be traced separately.
A meaningful comparison must specify the year, the payer, the recipient and whether a figure refers to tax, sponsorship or distributed surplus. Combining those flows would overstate what any one funding channel provided.

Valletta, Malta. Illustrative photograph of the island that became a base for international online gambling businesses.
Malta and the Online Disruption
Malta’s 2001 legislation and the Remote Gaming Regulations of 2004 are separate milestones. The latter established the remote-gaming framework discussed here; the Maltese authority’s contemporary account dates publication to May 2004. Source: Malta Gaming Authority, October 2005.
Malta became one base from which operators could develop international businesses. It was not a legal passport to every European market. Sweden’s licensing reform addressed the broader problem of gambling directed at Swedish consumers from outside the existing domestic system. The reform proposition set out the new licensing approach.
Different Nordic Paths
Denmark: betting and online casino opened to licensed competition on 1 January 2012. The change was partial: lotteries retained a different regulatory structure. Source: Spillemyndigheden.
Finland: the government’s March 2025 proposal envisaged opening betting and online casino-related products in 2027, while retaining exclusive rights for lotteries and other categories. It was not a proposal to end every monopoly. Source: Finnish Government, 20 March 2025.
Sweden: even after Casino Cosmopol closed, state-exclusive gambling remained for certain lotteries and value-token machines. Source: Spelinspektionen.
Summary: A Mixed Market
Casino Cosmopol’s closure was a significant institutional change, but it was not the final disappearance of state-exclusive gambling. The more accurate conclusion is that Sweden developed a mixed market with different rules for different products.
For marketing, the continuing issue is how commercial persuasion fits within consumer protection and public oversight. Ownership alone does not answer that question; the evidence lies in the products, the messages, the rules and their enforcement.
Sources and editorial correction
- Swedish Parliament — Proposition 2017/18:220, licensing reform
- Malta Gaming Authority — Remote Gaming Regulations, 2004
- Svenska Spel — Casino Cosmopol Stockholm closure, 25 April 2025
- Spelinspektionen — 2023 review, advertising measurement
- Swedish Parliament — September 2025 proposal on gambling credit
- Finnish Government — reform proposal, 20 March 2025
Correction — 14 October 2026: We corrected the scope of Sweden’s 2019 reform and Casino Cosmopol’s closure, Malta’s regulatory chronology, the status of the 2025 credit proposal and the description of Finland’s proposal. We removed an unverified attributed quotation and unsupported survey and funding claims, and clarified the measure behind the advertising figures. The article retains its historical scope through 2025. The earlier timeline graphic has been replaced with sourced dates.